An employee’s offer letter says $1,000 a week. Their first check is for $760. They come to you confused, maybe a little annoyed. Where did the other $240 go?
Nowhere bad, and nowhere you kept it. That gap is the most misunderstood thing in payroll, and once you can explain it in thirty seconds, half the awkward paycheck conversations disappear. So let’s follow one dollar of gross pay all the way to the bank.
The short answer
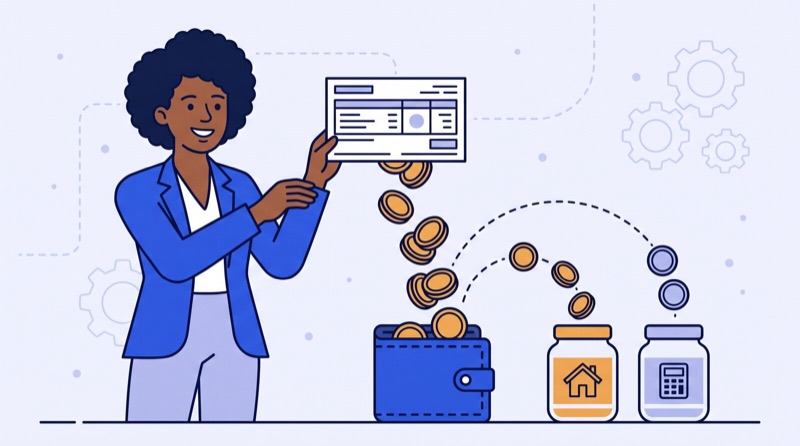
Gross pay is what someone earns before anything comes out. Net pay is what lands in their account. In between, the money makes four stops: pre-tax deductions, income tax withholding, the employee’s share of Social Security and Medicare, and any post-tax deductions. None of it is the employer’s to keep. Most of it is being sent on to the government or to the employee’s own benefits.
Stop 1: gross pay
This is the starting number. For an hourly worker it’s hours times rate, plus any overtime. For a salaried worker it’s their salary divided across pay periods. Bonuses, commissions, and tips get added here too. Everything downstream is calculated off this figure, so if gross pay is wrong, the whole check is wrong.
Stop 2: pre-tax deductions
Before a dollar gets taxed, certain deductions come out first. The common ones are contributions to a traditional retirement plan and the employee’s share of health insurance premiums.
Why the order matters: these lower the amount of income that gets taxed. If someone earns $1,000 and puts $100 into pre-tax benefits, they’re only taxed on $900. That’s the actual reason “pre-tax” is a benefit, and it’s a great thing to be able to explain to an employee who’s deciding whether to enroll.
Stop 3: tax withholding
Now the taxes. This is usually the biggest chunk, and it splits into two very different kinds.
Income tax. Federal income tax, and state income tax if your state has one. How much comes out depends on what the employee put on their W-4 and where they live. This is money withheld against the income tax they’ll owe for the year, which is why it can change if they update their W-4.
FICA: Social Security and Medicare. These are flat-percentage taxes on wages, split between employee and employer. The employee’s share comes out of this check. Their half is a fixed rate, not based on their W-4, which is why two people with very different withholding still have the same FICA percentage taken out.
Here’s the part employees almost never realize: the money withheld here isn’t a fee the business charges. You’re collecting it on the government’s behalf and passing it along. That’s also why falling behind on it is so serious, which is the whole story in the lesson on late payroll taxes.
Stop 4: post-tax deductions
A few things come out after taxes are calculated. Roth retirement contributions, certain insurance products, and wage garnishments (like a court-ordered child support order) usually sit here. They reduce the take-home amount but don’t lower taxable income the way pre-tax deductions do.
What’s left: net pay
Whatever survives all four stops is net pay, the number on the check. In our example, the $1,000 became $760 after benefits and withholding. The employee didn’t lose $240. They pre-funded their own benefits and prepaid taxes they were going to owe anyway.
The stop the employee never sees
Here’s what makes payroll cost more than people expect. Everything above happens inside the employee’s $1,000. But the employer has its own separate set of taxes that never appear on the paycheck at all:
- The employer’s matching share of Social Security and Medicare (the same rate the employee paid)
- Federal unemployment tax (FUTA)
- State unemployment tax (SUI)
So that $1,000 employee doesn’t cost the business $1,000. It costs $1,000 plus the employer’s share on top. When owners budget for a new hire using just the wage, this is the line they forget, and it’s a meaningful number. Plan for an employee to cost noticeably more than their stated pay.
Why this one concept is worth knowing cold
Understand gross-to-net and a surprising amount of payroll stops being confusing. You can answer the “where did my money go” question on the spot. You can budget a hire honestly. And you can spot when a check looks wrong, because you know what the pieces are supposed to be.
It’s the foundation everything else sits on, which is why it’s where the training program starts. Want it walked through with your own numbers? Book a free intro call and we’ll go line by line.
This is general education, not tax advice for your specific situation. Rates and rules change, so confirm the current figures before you rely on them.
Frequently asked
What's the difference between gross pay and net pay?
Gross pay is the total an employee earns before anything comes out. Net pay is what's left after deductions and taxes, the amount that actually hits their bank account. The gap between the two is withholding and deductions, not money the employer keeps.
What gets taken out of a paycheck?
In order: pre-tax deductions like retirement or health premiums, then federal and state income tax withholding, then the employee's share of Social Security and Medicare, then any post-tax deductions. The order matters because pre-tax items lower the income that gets taxed.
Does payroll cost the employer more than the employee's wage?
Yes. On top of gross wages, the employer pays its own matching share of Social Security and Medicare plus federal and state unemployment taxes. A good rule of thumb is that an employee costs noticeably more than their stated pay once employer taxes are added.